
Learning How to Pay Off Debt Faster starts with having a clear plan. Whether you’re dealing with credit card balances, personal loans, or multiple monthly payments, the right strategy can help you take control of your finances and potentially save money on interest.
Two popular debt repayment strategies are the debt snowball method, which focuses on paying off smaller balances first, and the debt avalanche method, which prioritizes debts with the highest interest rates. In some situations, a debt consolidation loan may also help simplify your payments.
In this guide, we’ll explain how to pay off debt faster, compare these repayment methods, and explore when consolidating debt with a personal loan might make sense.
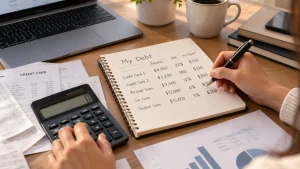
First, Understand Your Debt Before Making a Plan
Before choosing a repayment strategy, you need to understand exactly how much you owe.
Start by creating a list of your outstanding debts, including:
- Current balance: How much money you still owe.
- Interest rate (APR): The annual percentage rate charged on each debt.
- Minimum monthly payment: The amount required to keep your account current.
- Payment due date: When each payment must be made.
Having this information organized makes it easier to identify which debts are costing you the most and where you should focus your efforts.
If you’re unsure about an interest rate or payment amount, review your latest statement or contact your lender.
How to Pay Off Debt Faster by Adjusting Your Budget
One of the most effective ways to pay off debt faster is to consistently pay more than the minimum required amount.
Even small additional payments can reduce your outstanding balance and help lower the amount of interest you pay over time.
Consider these practical ways to free up money in your monthly budget:
- Review recurring expenses: Cancel subscriptions or services you no longer use.
- Reduce unnecessary spending: Temporarily cut back on dining out, entertainment, or impulse purchases.
- Use additional income: Put bonuses, overtime earnings, or side-job income toward your debt.
- Set a monthly repayment goal: Choose an extra amount you can realistically contribute each month.
The key is consistency. Making additional payments regularly can help you reach your financial goals sooner without making drastic changes to your lifestyle.
Debt Snowball vs. Debt Avalanche: Which Method Works Better?
When researching how to pay off debt faster, you’ll often come across two common repayment strategies: the debt snowball and the debt avalanche.
Both methods involve making minimum payments on all your debts while directing extra money toward one balance at a time.
The main difference is how you decide which debt to pay off first.
How the Debt Snowball Method Works
The debt snowball method focuses on paying off your smallest debt first, regardless of its interest rate.
Here’s how it works:
- List your debts from the smallest balance to the largest.
- Continue making minimum payments on every debt.
- Put any additional money toward the smallest balance.
- Once that debt is paid off, redirect its payment toward the next smallest balance.
- Repeat until all your debts are paid.
Best for: People who want to see progress quickly and stay motivated through small financial victories.
Paying off a smaller debt can give you a sense of accomplishment and encourage you to continue following your repayment plan.
How the Debt Avalanche Method Works
The debt avalanche method prioritizes debts with the highest interest rates rather than the smallest balances.
Follow these steps:
- List your debts from the highest interest rate to the lowest.
- Make minimum payments on all outstanding balances.
- Direct extra money toward the debt with the highest APR.
- Once that debt is paid off, move to the next highest-interest debt.
- Continue until all balances are eliminated.
Best for: People who want to minimize interest costs and are comfortable following a longer-term repayment strategy.
Because high-interest debts are addressed first, this method generally reduces the total interest paid compared with the snowball method, assuming the same payment amounts.
Which Debt Repayment Strategy Should You Choose?
Both methods can help you pay off debt faster, but the right choice depends on your financial situation and personal preferences.
The debt snowball may be more effective if you need motivation from paying off individual accounts quickly.
The debt avalanche may be a better option if your priority is saving money on interest.
You can also combine the approaches by paying off one small debt first to build momentum, then switching to the avalanche method.
Ultimately, the best strategy is one you can follow consistently.
Can a Debt Consolidation Loan Help You Pay Off Debt Faster?
If you’re managing several outstanding balances, a debt consolidation loan may be another option worth exploring.
Debt consolidation involves taking out a new loan to pay off multiple existing debts. Instead of managing several payments with different due dates and interest rates, you make one monthly payment toward the new loan.
Depending on the loan terms, consolidation may offer benefits such as:
- Simplified payments: Manage one monthly payment instead of several.
- Potential interest savings: A lower interest rate may reduce borrowing costs.
- Predictable repayment: A fixed-rate loan can provide consistent monthly payments.
- Clear repayment timeline: A defined loan term helps you understand when your debt could be paid off.
However, consolidation doesn’t automatically mean you’ll pay off debt faster. The outcome depends on the new loan’s interest rate, fees, repayment term, and your financial habits.
What to Consider Before Consolidating Debt
Before applying for a debt consolidation loan, ask yourself:
- Is the new interest rate lower than the rates on my existing debts?
- Are there origination fees or other borrowing costs?
- Will the new monthly payment fit comfortably within my budget?
- How much interest will I pay over the entire loan term?
- Can I avoid accumulating new credit card balances after consolidation?
A lower monthly payment may seem attractive, but extending the repayment period could increase the total amount of interest you pay.
For a closer look at this option, read our guide on consolidating debt with a personal loan.
5 Practical Habits to Help You Pay Off Debt Faster
Choosing a repayment method is important, but your everyday financial habits also influence how quickly you can reduce your balances.
1. Automate Your Monthly Payments
Setting up automatic payments helps you avoid missed due dates and potential late fees.
Whenever possible, schedule at least the minimum payment for each account and make additional payments toward your priority debt.
2. Make Payments When You Get Paid
Instead of waiting until the end of the month, consider setting aside your debt repayment money as soon as you receive your paycheck.
This can help you stay consistent and reduce the temptation to spend money intended for debt payments.
3. Avoid Taking on New Debt
Continuing to use credit cards while trying to pay down existing balances can slow your progress.
Try limiting unnecessary borrowing until your outstanding debts become more manageable.
4. Build a Small Emergency Fund
Unexpected expenses can make it difficult to stay on track.
Setting aside a small emergency fund may help you handle minor financial surprises without relying on additional credit.
5. Review Your Progress Every Month
Track how much you’ve paid, which balances have decreased, and whether you can contribute more toward your repayment goals.
Reviewing your plan regularly can help you identify opportunities to pay off debt faster.
If you’re already struggling to keep up with monthly expenses, our article on what to do when expenses start falling behind offers additional guidance.
Frequently Asked Questions About How to Pay Off Debt Faster
What is the best way to pay off multiple debts?
The best approach is to organize your outstanding balances, continue making minimum payments, and direct extra money toward one debt at a time. The debt snowball and debt avalanche methods are both useful strategies.
How can I pay off debt faster with a limited income?
Start by reviewing your monthly expenses and identifying small amounts you can consistently put toward debt. Reducing unnecessary spending, avoiding new borrowing, and making additional payments when possible can help you make progress.
Is the debt snowball or debt avalanche better?
The debt avalanche generally saves more money on interest, while the debt snowball offers quicker wins that may help you stay motivated. The better option depends on your financial priorities and which strategy you can maintain.
Does paying off debt faster improve your credit score?
Reducing outstanding balances and making payments on time can positively influence your credit profile. However, the effect on your credit score depends on several factors, including your credit utilization, payment history, and overall credit accounts.
Should I get a personal loan to pay off debt?
A personal loan may be worth considering if it offers more manageable payments, better terms, or lower overall borrowing costs. Always compare interest rates, fees, and repayment periods before deciding.
Explore Your Debt Consolidation Options With Inter-America Finance
Understanding how to pay off debt faster is the first step toward building a more manageable financial future.
Whether you choose the debt snowball, debt avalanche, or explore debt consolidation, having a realistic repayment plan can help you move forward with greater confidence.
If you’re considering a personal loan to simplify your monthly payments, Inter-America Finance can help you explore your available options.
Our team serves customers in the El Paso area and can answer questions about personal loans and the application process.
You can start your pre-approval online or call (915) 351-3900 to speak with a local branch.
This article is for general informational purposes only and does not constitute financial advice. Loan approval, rates, and terms depend on each applicant’s individual circumstances.
 English
 Spanish